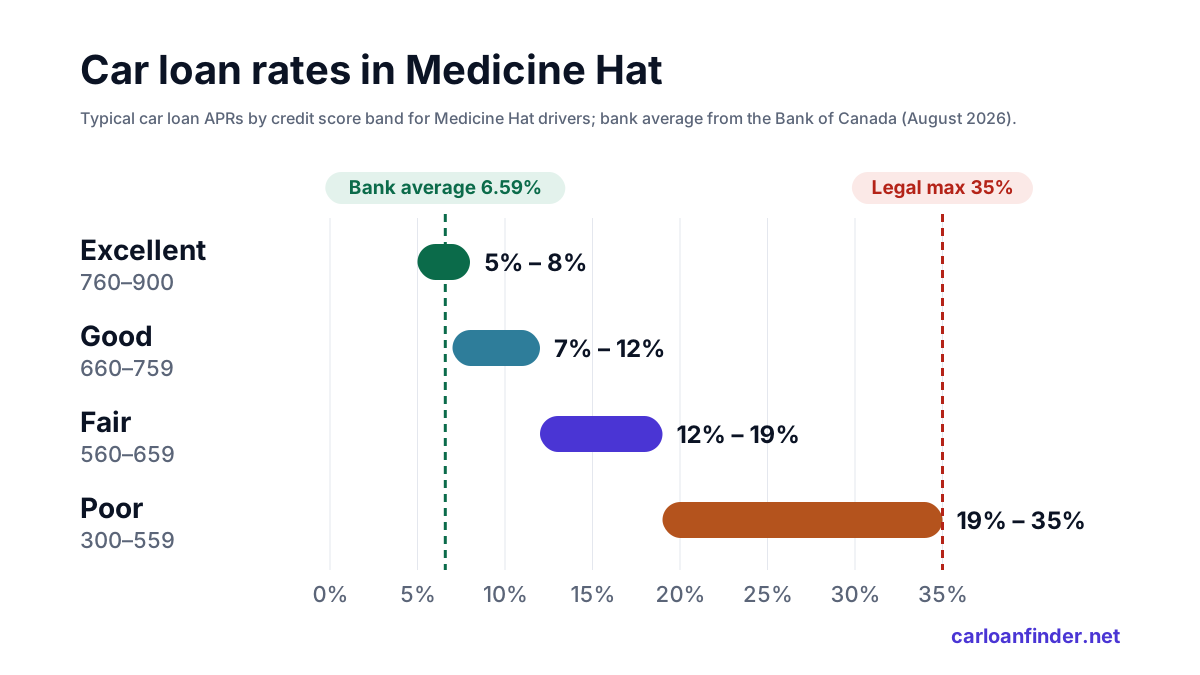
When your credit is less than perfect, the contract matters as much as the approval. In Medicine Hat, specialist lenders and dealer finance offices can say yes after a bank has said no, but the offer you get deserves a careful read. Rates follow your Equifax band: published estimates run 7–12% for good credit, 12–19% for fair and 19–35% for poor, against a 6.59% bank average in August 2026. This page explains what Alberta’s dealer regulator does for you, the lines in a loan agreement worth checking twice, and what a good-credit rate costs at each term, so you can tell a fair offer from a padded one.
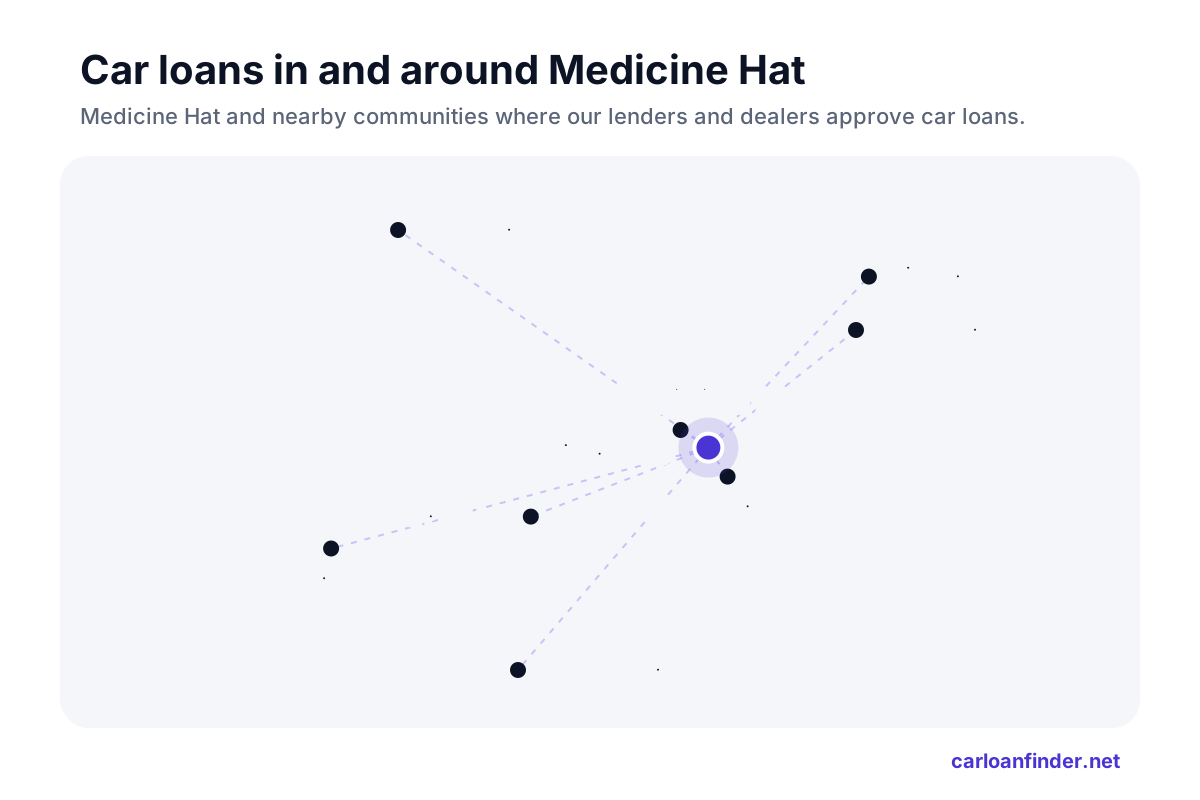
Medicine Hat is covered by three postal areas, T1A, T1B and T1C, and the way lenders assess you is the same in each. The city is about 266 km from Calgary, Alberta’s largest city. Redcliff (9 km) and Dunmore (10 km) are right next door, with Schuler (52 km), Bow Island (53 km), Hilda (65 km), Foremost (82 km), Brooks (105 km) and Taber (109 km) farther out. If you live in one of those communities, the dealer you choose can be wherever the right vehicle is; your application is judged on your income and credit, not your town.
Facts reviewed October 29, 2026 · See sources
What interest rate can you get in Medicine Hat?
Most bank car loans are priced above prime. Dealer-arranged and specialist lenders set their own fixed rates, which is why credit score matters more than the Bank of Canada rate for bad credit borrowers.
| Credit tier | Equifax score | Typical APR | Example payment* |
|---|---|---|---|
| Excellent | 760–900 | 5% – 8% | $420/mo |
| Good | 660–759 | 7% – 12% | $457/mo |
| Fair | 560–659 | 12% – 19% | $535/mo |
| Poor | 300–559 | 19% – 35% | $704/mo |
| Legal maximum | — | 35% APR | Criminal Code, s. 347 |
* Score bands from Equifax Canada. Rate ranges are estimates published by Loans Canada, not quotes; your rate depends on income, debts, down payment, term and the vehicle. Example payment: $25,000 over 72 months at the middle of each range.
What a car loan costs in Medicine Hat
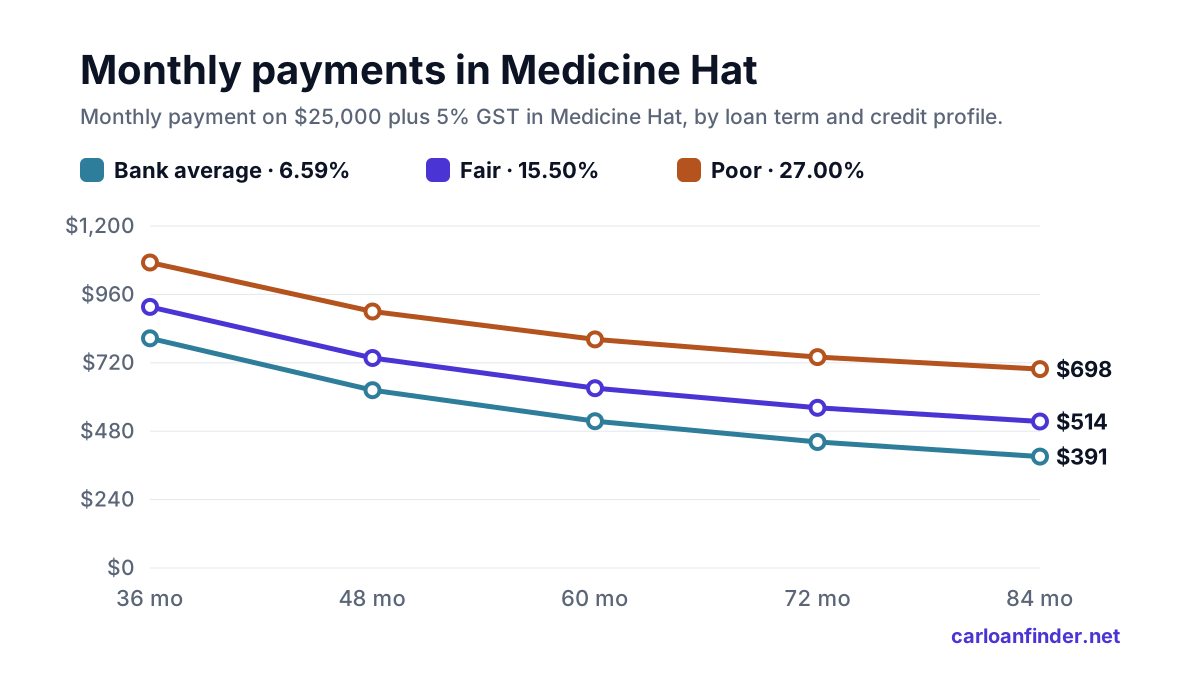
| Credit profile | 48 months | 60 months | 72 months | 84 months | Interest (72 mo) |
|---|---|---|---|---|---|
| Bank average 6.59% APR | $594 | $490 | $421 | $372 | $5,335 |
| Good 9.50% APR | $628 | $525 | $457 | $409 | $7,894 |
| Fair 15.50% APR | $702 | $601 | $535 | $489 | $13,551 |
| Poor 27.00% APR | $857 | $763 | $704 | $665 | $25,719 |
Monthly payment on $25,000 before tax, using the Bank of Canada average for bank borrowers and the middle of each published credit-tier range. In Alberta, 5% GST adds about $1,250 if it is financed.
Compare car lenders in Medicine Hat
Where you borrow matters as much as your credit score. Banks and credit unions usually offer the lowest rates but expect good credit; specialist lenders approve more credit profiles at higher rates. Here is how the options compare.
| Lender | Best for | How rates are set | Watch out for |
|---|---|---|---|
| Bank | Good to excellent credit | Usually priced above prime; close to the 6.59% bank average | Stricter approval; may require a larger down payment with lower scores |
| Credit union | Members with fair to good credit | Set by each credit union; often competitive with banks | Membership required; rules vary by province |
| Manufacturer finance | New vehicles, good credit | Promotional rates set by the automaker | A low rate may replace a cash rebate — compare both |
| Specialist (subprime) lender | Bad credit, proposals, newcomers | Higher fixed rates, up to the 35% legal maximum | Read the total cost of borrowing before you sign |
| Buy here, pay here dealer | When other lenders decline | Often the highest rates allowed | Limited vehicle choice; payments may not be reported to credit bureaus |
| Car Loan Finder | Every credit profile | Matched to lenders for your credit situation | One application; no impact on your credit score to see options |
Your Medicine Hat car loan, step by step
- 1 Check your credit report You can get your credit report free from both Equifax and TransUnion. Dispute any errors before a lender sees them.
- 2 Set your budget Use the payment table above to find a payment that leaves room for insurance, fuel and maintenance.
- 3 Get pre-approved A pre-approval shows your likely rate and limit before you choose a car. Checking your options with Car Loan Finder is a soft inquiry.
- 4 Compare the total cost of borrowing Lenders must disclose the APR and total cost of borrowing in writing. Compare that figure, not only the monthly payment.
- 5 Keep the term as short as you can afford Longer terms lower the payment but cost more interest and raise the risk of owing more than the car is worth.
Your credit situation, explained
Bankruptcy or consumer proposal
A first bankruptcy usually stays on your Equifax report for 6 years after discharge; a consumer proposal stays until 3 years after you complete it. Specialist lenders can approve you before those dates — often with a down payment.
No credit history
If you are new to Canada or have never borrowed, lenders look at income, employment and residency instead of a score. A larger down payment or a co-signer improves your options.
Self-employed
Expect to show recent bank statements and your Notices of Assessment from the Canada Revenue Agency instead of pay stubs.
Rebuilding after missed payments
On-time car payments are reported to the credit bureaus by most lenders. Choosing a payment you can always make is the fastest way to rebuild.
What AMVIC licensing means for you
Car dealers in Alberta are regulated by AMVIC (Alberta Motor Vehicle Industry Council). Before you sign, check that the dealer is licensed or registered with AMVIC. That way, if the vehicle or the deal turns out to be different from what you were told, you have a regulator to contact.
Licensing does not set your interest rate or make a loan affordable, so it is not a substitute for reading the paperwork. What it does give you is somewhere to turn if the vehicle or its financing was misrepresented. Keep copies of the bill of sale, the loan agreement and any written promises in case you need them later.
Lines in the contract worth checking twice
Start with the annual percentage rate and the total cost of borrowing; both must be stated in writing. Then confirm the amount financed: the vehicle price, the 5% GST, any fees, and any balance from a trade-in. If the amount is higher than you expected, ask for a line-by-line explanation before going further.
Look for optional products added to the loan, such as an extended service contract or credit insurance. They raise the amount you borrow and the interest you pay. Ask whether any of them is a condition of approval, and have anything you do not want removed. Finally, check whether you can pay the loan off early without a penalty.
Good-credit payments at every term
If your score sits in the good band (660–759), published estimates put your rate at 7–12%. At 9.50%, $25,000 works out to about $628 a month over 48 months, $525 over 60, $457 over 72 and $409 over 84. For comparison, the 6.59% bank average over 48 months is about $594.
Even with good credit, a longer term costs real money. At the bank average, 84 months instead of 60 adds about $1,863 in interest on $25,000. Insurance comes from private insurers in Alberta and full coverage is required before delivery, so price it into the monthly total before choosing a term.
Local costs and protections in Alberta
- Auto insurance in Alberta is sold by private insurers, so compare several quotes. Lenders need proof of full coverage before you take delivery.
- Car dealers in Alberta are regulated by AMVIC (Alberta Motor Vehicle Industry Council). Check that the dealer is licensed or registered before you sign, and contact the regulator if something goes wrong.