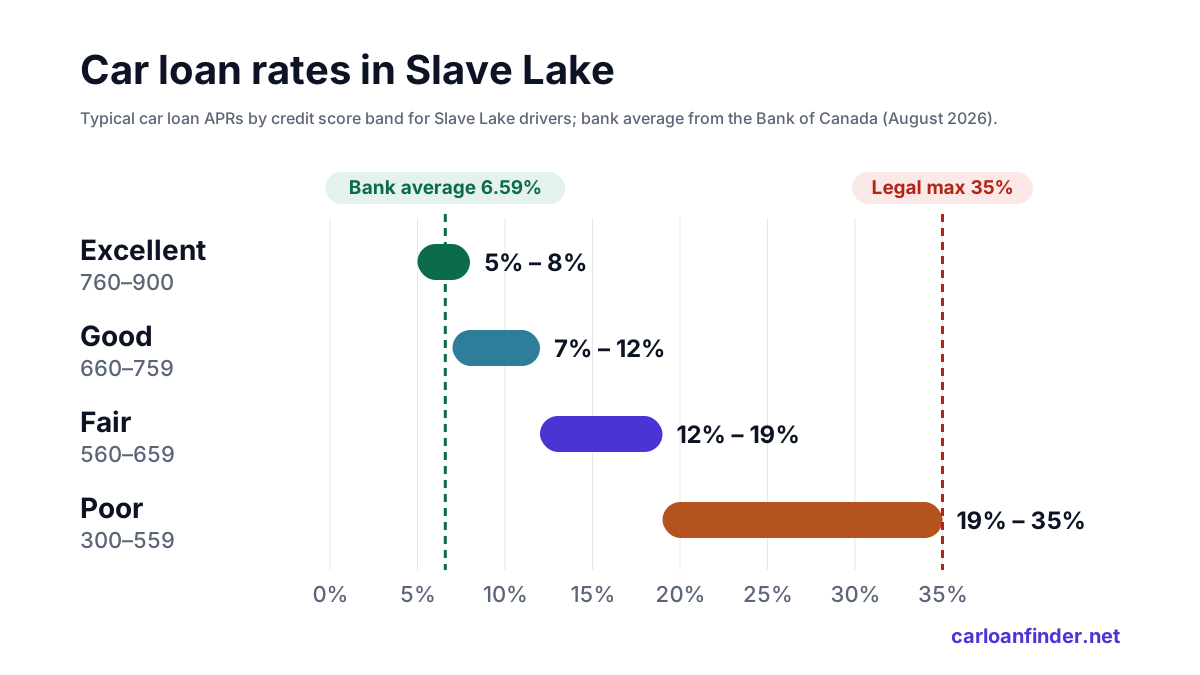
What you pay on a car loan in Slave Lake comes down to three things: your credit score, the vehicle and the term. Published estimates by Equifax score band run from 5–8% for excellent credit to 19–35% for poor credit, and the Bank of Canada's average for new auto loans at chartered banks was 6.59% in August 2026. Car Loan Finder is not a lender. We show you which lenders suit your file, using a soft inquiry that does not touch your credit score.
Swan Hills is about 75 km from Slave Lake and Wabasca about 95 km, while High Prairie is about 110 km and Athabasca about 114 km away. With that much distance between towns, the vehicle you choose needs to be dependable, and a sound loan matters just as much. Slave Lake's postal area is T0G, and Calgary, Alberta's largest city, is about 473 km away.
Facts reviewed October 29, 2026 · See sources
Typical auto loan rates in Slave Lake
Most bank car loans are priced above prime. Dealer-arranged and specialist lenders set their own fixed rates, which is why credit score matters more than the Bank of Canada rate for bad credit borrowers.
| Credit tier | Equifax score | Typical APR | Example payment* |
|---|---|---|---|
| Excellent | 760–900 | 5% – 8% | $420/mo |
| Good | 660–759 | 7% – 12% | $457/mo |
| Fair | 560–659 | 12% – 19% | $535/mo |
| Poor | 300–559 | 19% – 35% | $704/mo |
| Legal maximum | — | 35% APR | Criminal Code, s. 347 |
* Score bands from Equifax Canada. Rate ranges are estimates published by Loans Canada, not quotes; your rate depends on income, debts, down payment, term and the vehicle. Example payment: $25,000 over 72 months at the middle of each range.
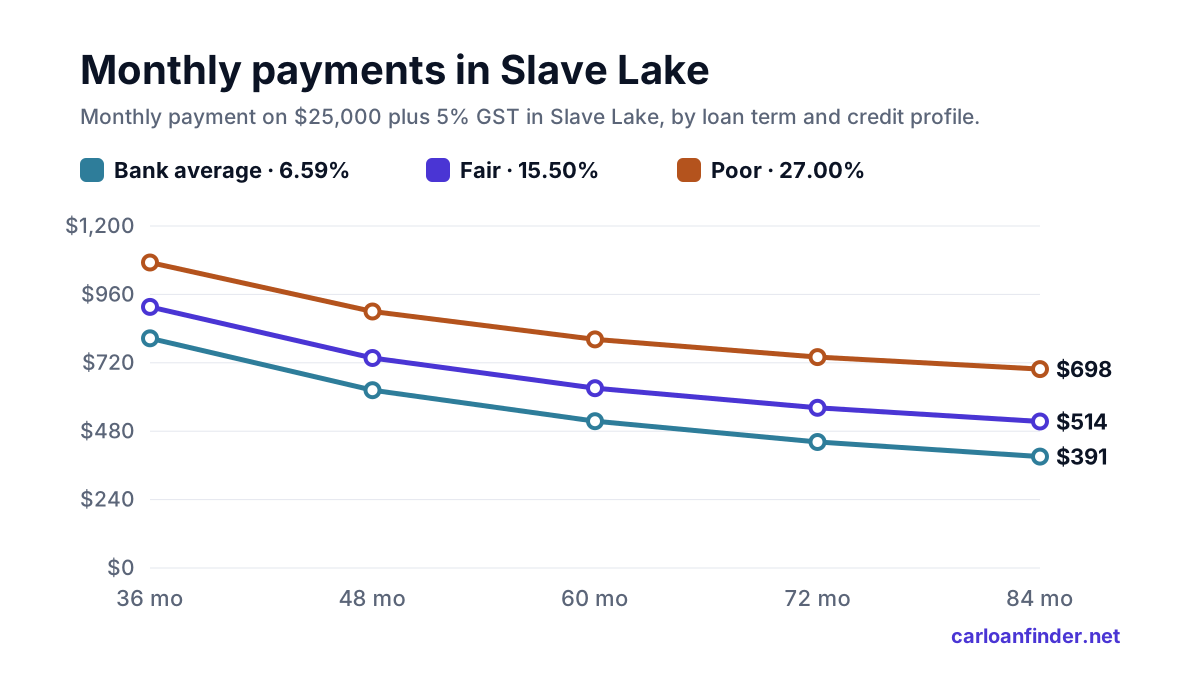
Monthly payments on a Slave Lake car loan
| Credit profile | 48 months | 60 months | 72 months | 84 months | Interest (72 mo) |
|---|---|---|---|---|---|
| Bank average 6.59% APR | $594 | $490 | $421 | $372 | $5,335 |
| Good 9.50% APR | $628 | $525 | $457 | $409 | $7,894 |
| Fair 15.50% APR | $702 | $601 | $535 | $489 | $13,551 |
| Poor 27.00% APR | $857 | $763 | $704 | $665 | $25,719 |
Monthly payment on $25,000 before tax, using the Bank of Canada average for bank borrowers and the middle of each published credit-tier range. In Alberta, 5% GST adds about $1,250 if it is financed.
Compare car lenders in Slave Lake
Where you borrow matters as much as your credit score. Banks and credit unions usually offer the lowest rates but expect good credit; specialist lenders approve more credit profiles at higher rates. Here is how the options compare.
| Lender | Best for | How rates are set | Watch out for |
|---|---|---|---|
| Bank | Good to excellent credit | Usually priced above prime; close to the 6.59% bank average | Stricter approval; may require a larger down payment with lower scores |
| Credit union | Members with fair to good credit | Set by each credit union; often competitive with banks | Membership required; rules vary by province |
| Manufacturer finance | New vehicles, good credit | Promotional rates set by the automaker | A low rate may replace a cash rebate — compare both |
| Specialist (subprime) lender | Bad credit, proposals, newcomers | Higher fixed rates, up to the 35% legal maximum | Read the total cost of borrowing before you sign |
| Buy here, pay here dealer | When other lenders decline | Often the highest rates allowed | Limited vehicle choice; payments may not be reported to credit bureaus |
| Car Loan Finder | Every credit profile | Matched to lenders for your credit situation | One application; no impact on your credit score to see options |
How to get approved in Slave Lake with bad credit
- 1 Know your score band Canadian credit scores range from 300 to 900. Find your Equifax band in the rate table to estimate your rate.
- 2 Gather documents Recent pay stubs or bank statements, a valid driver’s licence and proof of your Slave Lake address.
- 3 Apply once, compare offers One application can reach several lenders, so you avoid multiple hard credit checks.
- 4 Watch for add-ons Extended warranties and insurance products added to the loan increase what you borrow. Ask for prices separately.
- 5 Sign only when the numbers match Check that the APR, term and total cost of borrowing on the contract match what you were quoted.
Bankruptcy, proposals, newcomers and more
Bankruptcy or consumer proposal
A first bankruptcy usually stays on your Equifax report for 6 years after discharge; a consumer proposal stays until 3 years after you complete it. Specialist lenders can approve you before those dates — often with a down payment.
No credit history
If you are new to Canada or have never borrowed, lenders look at income, employment and residency instead of a score. A larger down payment or a co-signer improves your options.
Self-employed
Expect to show recent bank statements and your Notices of Assessment from the Canada Revenue Agency instead of pay stubs.
Rebuilding after missed payments
On-time car payments are reported to the credit bureaus by most lenders. Choosing a payment you can always make is the fastest way to rebuild.
How your score band sets the rate
Lenders group scores into bands. On Equifax's scale, 760–900 is excellent, with estimated rates of 5–8%; 660–759 is good, at 7–12%; 560–659 is fair, at 12–19%; and 300–559 is poor, at 19–35%. Where you land within a band depends on income, debts and the vehicle.
Bank rates follow the Bank of Canada. Its policy rate was 2.25% in October 2026 and prime was 4.45%. Specialist lenders price above those levels for lower scores, but no lender may charge more than 35% APR under the Criminal Code.
Good-credit payments over different terms
At 9.50%, a $25,000 loan costs about $628 a month over 48 months, $525 over 60, $457 over 72 and $409 over 84. Each step down in payment adds interest and stretches the time you owe more than the vehicle is worth.
Choose the vehicle with the term in mind. A newer, lower-mileage model can justify a longer loan, while an older one is better paired with a shorter term so the loan does not outlast the car you are paying for.
Insurance and paperwork before you buy
Auto insurance in Alberta is sold by private insurers, and quotes for the same driver can vary a lot. Lenders need proof of full coverage before delivery, so ask for quotes on the exact vehicle you plan to buy before you settle on a price.
Whether you buy in Slave Lake or travel to Athabasca or High Prairie, confirm the dealer is licensed by AMVIC (Alberta Motor Vehicle Industry Council). Keep copies of every document and contact AMVIC if anything in the sale is misrepresented.
Before you sign in Alberta
- Auto insurance in Alberta is sold by private insurers, so compare several quotes. Lenders need proof of full coverage before you take delivery.
- Car dealers in Alberta are regulated by AMVIC (Alberta Motor Vehicle Industry Council). Check that the dealer is licensed or registered before you sign, and contact the regulator if something goes wrong.