Bank of Canada announcements make the news, yet the rate you are offered on a car loan in Trail depends far more on your credit file than on headlines. Car Loan Finder helps first-time buyers and people with damaged credit find lenders and dealers that suit their situation. We are not a lender, and our check is a soft inquiry that does not affect your score. You see likely rates and payments before choosing to apply anywhere.
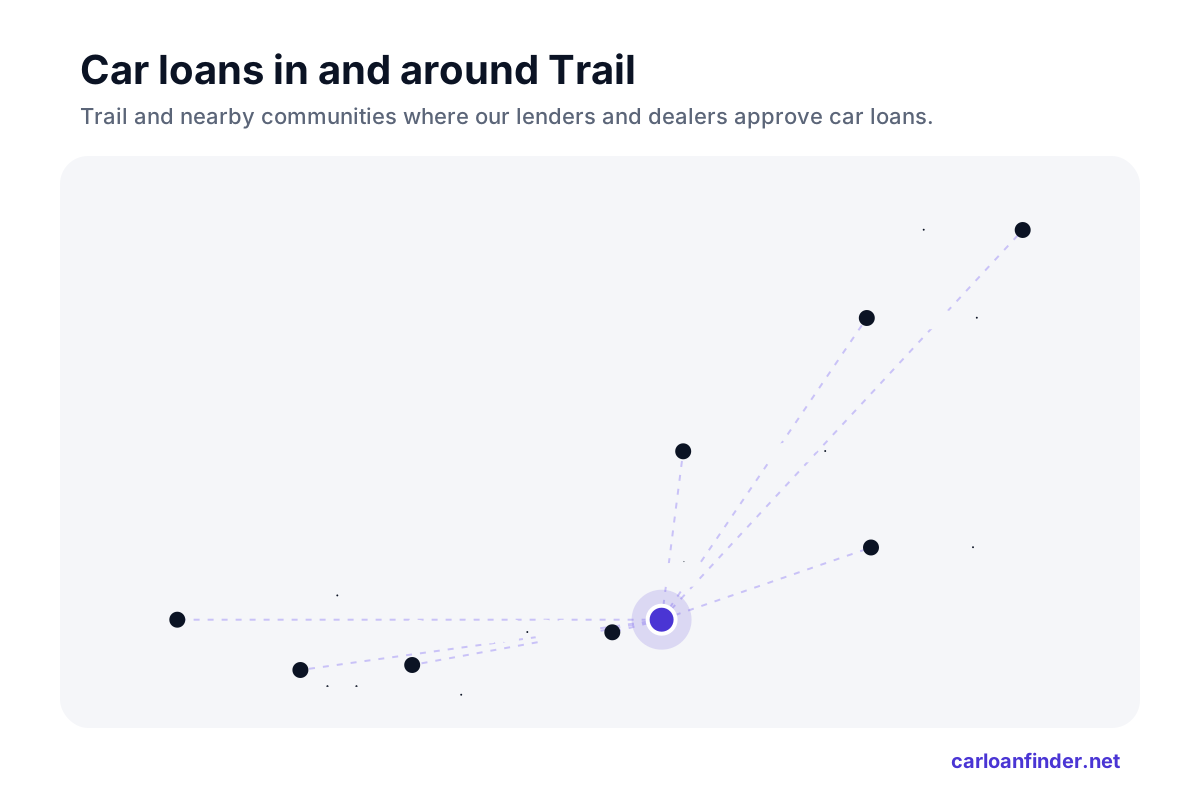
Rossland is only about 8 km from Trail, Castlegar about 25 km and Salmo about 33 km, giving you a few communities nearby to compare vehicles. Christina Lake sits about 37 km away, and Grand Forks and Nelson are each about 54 km out. Trail is covered by the V1R postal area and is about 394 km from Vancouver, British Columbia's largest city. Any dealer you deal with should hold a licence from the Vehicle Sales Authority of British Columbia (VSA).
Facts reviewed October 29, 2026 · See sources
What interest rate can you get in Trail?
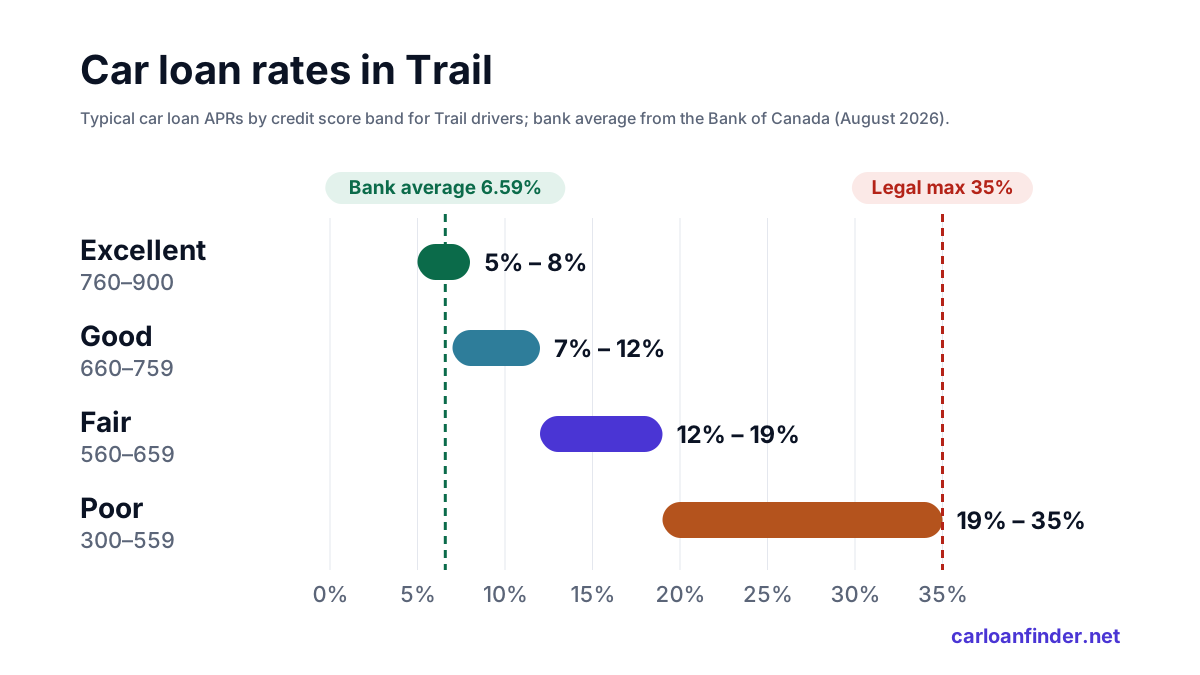
Most bank car loans are priced above prime. Dealer-arranged and specialist lenders set their own fixed rates, which is why credit score matters more than the Bank of Canada rate for bad credit borrowers.
| Credit tier | Equifax score | Typical APR | Example payment* |
|---|---|---|---|
| Excellent | 760–900 | 5% – 8% | $420/mo |
| Good | 660–759 | 7% – 12% | $457/mo |
| Fair | 560–659 | 12% – 19% | $535/mo |
| Poor | 300–559 | 19% – 35% | $704/mo |
| Legal maximum | — | 35% APR | Criminal Code, s. 347 |
* Score bands from Equifax Canada. Rate ranges are estimates published by Loans Canada, not quotes; your rate depends on income, debts, down payment, term and the vehicle. Example payment: $25,000 over 72 months at the middle of each range.
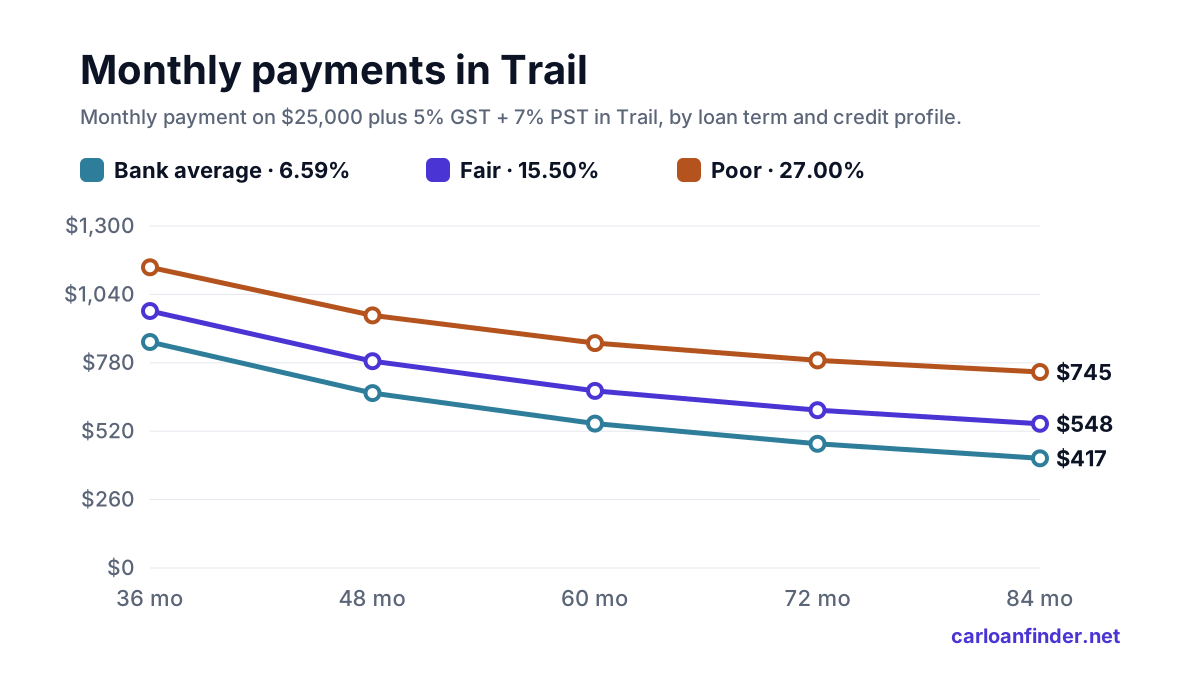
Monthly payments on a Trail car loan
| Credit profile | 48 months | 60 months | 72 months | 84 months | Interest (72 mo) |
|---|---|---|---|---|---|
| Bank average 6.59% APR | $594 | $490 | $421 | $372 | $5,335 |
| Good 9.50% APR | $628 | $525 | $457 | $409 | $7,894 |
| Fair 15.50% APR | $702 | $601 | $535 | $489 | $13,551 |
| Poor 27.00% APR | $857 | $763 | $704 | $665 | $25,719 |
Monthly payment on $25,000 before tax, using the Bank of Canada average for bank borrowers and the middle of each published credit-tier range. In British Columbia, 5% GST + 7% PST adds about $3,000 if it is financed.
Banks vs. specialist lenders in Trail
Where you borrow matters as much as your credit score. Banks and credit unions usually offer the lowest rates but expect good credit; specialist lenders approve more credit profiles at higher rates. Here is how the options compare.
| Lender | Best for | How rates are set | Watch out for |
|---|---|---|---|
| Bank | Good to excellent credit | Usually priced above prime; close to the 6.59% bank average | Stricter approval; may require a larger down payment with lower scores |
| Credit union | Members with fair to good credit | Set by each credit union; often competitive with banks | Membership required; rules vary by province |
| Manufacturer finance | New vehicles, good credit | Promotional rates set by the automaker | A low rate may replace a cash rebate — compare both |
| Specialist (subprime) lender | Bad credit, proposals, newcomers | Higher fixed rates, up to the 35% legal maximum | Read the total cost of borrowing before you sign |
| Buy here, pay here dealer | When other lenders decline | Often the highest rates allowed | Limited vehicle choice; payments may not be reported to credit bureaus |
| Car Loan Finder | Every credit profile | Matched to lenders for your credit situation | One application; no impact on your credit score to see options |
Your Trail car loan, step by step
- 1 Know your score band Canadian credit scores range from 300 to 900. Find your Equifax band in the rate table to estimate your rate.
- 2 Gather documents Recent pay stubs or bank statements, a valid driver’s licence and proof of your Trail address.
- 3 Apply once, compare offers One application can reach several lenders, so you avoid multiple hard credit checks.
- 4 Watch for add-ons Extended warranties and insurance products added to the loan increase what you borrow. Ask for prices separately.
- 5 Sign only when the numbers match Check that the APR, term and total cost of borrowing on the contract match what you were quoted.
Car loans for every credit situation
Bankruptcy or consumer proposal
A first bankruptcy usually stays on your Equifax report for 6 years after discharge; a consumer proposal stays until 3 years after you complete it. Specialist lenders can approve you before those dates — often with a down payment.
No credit history
If you are new to Canada or have never borrowed, lenders look at income, employment and residency instead of a score. A larger down payment or a co-signer improves your options.
Self-employed
Expect to show recent bank statements and your Notices of Assessment from the Canada Revenue Agency instead of pay stubs.
Rebuilding after missed payments
On-time car payments are reported to the credit bureaus by most lenders. Choosing a payment you can always make is the fastest way to rebuild.
Where rates stand in 2026
In October 2026, the Bank of Canada's policy rate was 2.25% and the prime rate was 4.45%. Chartered banks charged an average of 6.59% on new auto loans in August 2026 and 6.83% on existing ones. Those are bank averages, not the rates offered on bruised credit.
With a lower score, the rate is set mostly by your credit band. Published Equifax estimates run from 12–19% for fair credit to 19–35% for poor credit, and the Criminal Code has capped the annual cost of credit at 35% since January 1, 2025.
Starting with no credit file
If you have never had a loan or credit card, there is no score to check, so lenders look at your income, how long you have been employed and proof of residency. A larger down payment or a co-signer with established credit improves the offer.
Keep the first loan modest. At good credit of 9.50%, $25,000 over 72 months is $457 a month; a smaller amount and a payment you can always meet will build a solid record faster than stretching for a pricier vehicle.
Refinancing once your score improves
A high rate does not have to last the whole term. Most lenders report on-time payments to the credit bureaus, so after a year or more of steady payments you may qualify for a lower rate and can ask about refinancing the balance.
Before refinancing, check for any prepayment charges in your current contract and compare the total remaining cost, not just the new payment. On a long term, the gap is large: $665 a month at 27.00% over 84 months versus $372 at the bank average.
Before you sign in British Columbia
- Basic auto insurance in British Columbia is provided by ICBC, the public insurer. Lenders need proof of coverage before you take delivery, so get your ICBC quote early.
- Car dealers in British Columbia are regulated by the Vehicle Sales Authority of British Columbia (VSA). Check that the dealer is licensed or registered before you sign, and contact the regulator if something goes wrong.
- Winter tires (marked M+S or with the mountain-snowflake symbol) are required on most designated BC highways from October 1 to April 30. Check DriveBC for your routes.
- PST on passenger vehicles rises above 7% for higher purchase prices.