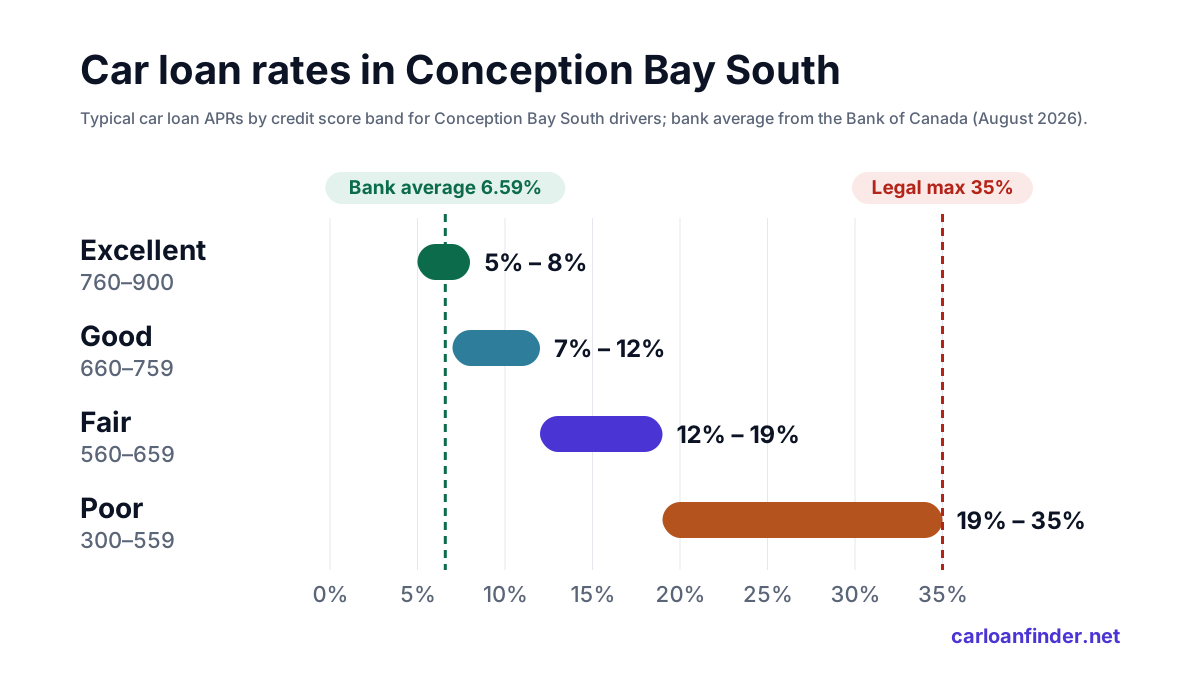
If a bank turned down your car loan in Conception Bay South, the usual next step is a specialist lender or a dealer's finance office, not giving up on the car. These lenders weigh your income, your residence and the payment you can handle as heavily as your score, and they set the rate by credit band. Published estimates put fair credit at 12–19% and poor credit at 19–35%, against a chartered-bank average of 6.59% in August 2026. After the rate itself, the decision that moves your cost most is the length of the loan, so this page puts term length front and centre.
Conception Bay South has 2 postal areas, A1W and A1X, and the application works the same in both. The town is about 23 km from St. John's, Newfoundland and Labrador's largest city, which puts a wide circle of dealers within comparison range. Paradise (9 km) and Mount Pearl (16 km) are closer, and communities around the bay are also within reach, among them Clarkes Beach (22 km), Bay Roberts (23 km), Spaniards Bay (25 km), Harbour Grace (27 km) and Carbonear (32 km).
Facts reviewed October 29, 2026 · See sources
What interest rate can you get in Conception Bay South?
Most bank car loans are priced above prime. Dealer-arranged and specialist lenders set their own fixed rates, which is why credit score matters more than the Bank of Canada rate for bad credit borrowers.
| Credit tier | Equifax score | Typical APR | Example payment* |
|---|---|---|---|
| Excellent | 760–900 | 5% – 8% | $420/mo |
| Good | 660–759 | 7% – 12% | $457/mo |
| Fair | 560–659 | 12% – 19% | $535/mo |
| Poor | 300–559 | 19% – 35% | $704/mo |
| Legal maximum | — | 35% APR | Criminal Code, s. 347 |
* Score bands from Equifax Canada. Rate ranges are estimates published by Loans Canada, not quotes; your rate depends on income, debts, down payment, term and the vehicle. Example payment: $25,000 over 72 months at the middle of each range.
How your credit score changes the payment
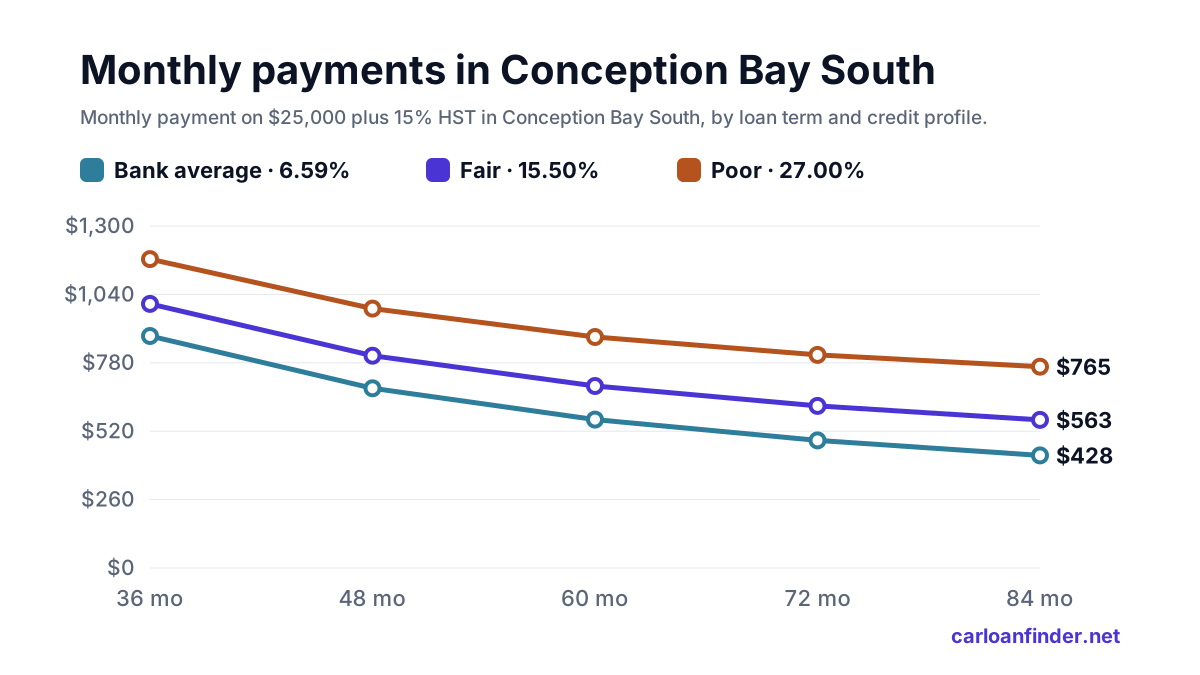
| Credit profile | 48 months | 60 months | 72 months | 84 months | Interest (72 mo) |
|---|---|---|---|---|---|
| Bank average 6.59% APR | $594 | $490 | $421 | $372 | $5,335 |
| Good 9.50% APR | $628 | $525 | $457 | $409 | $7,894 |
| Fair 15.50% APR | $702 | $601 | $535 | $489 | $13,551 |
| Poor 27.00% APR | $857 | $763 | $704 | $665 | $25,719 |
Monthly payment on $25,000 before tax, using the Bank of Canada average for bank borrowers and the middle of each published credit-tier range. In Newfoundland and Labrador, 15% HST adds about $3,750 if it is financed.
Which Conception Bay South lender fits your credit?
Where you borrow matters as much as your credit score. Banks and credit unions usually offer the lowest rates but expect good credit; specialist lenders approve more credit profiles at higher rates. Here is how the options compare.
| Lender | Best for | How rates are set | Watch out for |
|---|---|---|---|
| Bank | Good to excellent credit | Usually priced above prime; close to the 6.59% bank average | Stricter approval; may require a larger down payment with lower scores |
| Credit union | Members with fair to good credit | Set by each credit union; often competitive with banks | Membership required; rules vary by province |
| Manufacturer finance | New vehicles, good credit | Promotional rates set by the automaker | A low rate may replace a cash rebate — compare both |
| Specialist (subprime) lender | Bad credit, proposals, newcomers | Higher fixed rates, up to the 35% legal maximum | Read the total cost of borrowing before you sign |
| Buy here, pay here dealer | When other lenders decline | Often the highest rates allowed | Limited vehicle choice; payments may not be reported to credit bureaus |
| Car Loan Finder | Every credit profile | Matched to lenders for your credit situation | One application; no impact on your credit score to see options |
Getting approved in Conception Bay South: a practical plan
- 1 Know your score band Canadian credit scores range from 300 to 900. Find your Equifax band in the rate table to estimate your rate.
- 2 Gather documents Recent pay stubs or bank statements, a valid driver’s licence and proof of your Conception Bay South address.
- 3 Apply once, compare offers One application can reach several lenders, so you avoid multiple hard credit checks.
- 4 Watch for add-ons Extended warranties and insurance products added to the loan increase what you borrow. Ask for prices separately.
- 5 Sign only when the numbers match Check that the APR, term and total cost of borrowing on the contract match what you were quoted.
Your credit situation, explained
Bankruptcy or consumer proposal
A first bankruptcy usually stays on your Equifax report for 6 years after discharge; a consumer proposal stays until 3 years after you complete it. Specialist lenders can approve you before those dates — often with a down payment.
No credit history
If you are new to Canada or have never borrowed, lenders look at income, employment and residency instead of a score. A larger down payment or a co-signer improves your options.
Self-employed
Expect to show recent bank statements and your Notices of Assessment from the Canada Revenue Agency instead of pay stubs.
Rebuilding after missed payments
On-time car payments are reported to the credit bureaus by most lenders. Choosing a payment you can always make is the fastest way to rebuild.
Shopping beyond Conception Bay South
Financing is arranged around you, your income and the vehicle, not your postal code. That leaves you free to compare stock in Conception Bay South, Paradise, Mount Pearl and St. John's, or in towns around the bay such as Bay Roberts and Carbonear, before choosing. Checking your options first lets you walk onto a lot with a budget instead of a guess.
When you compare, compare the whole deal. Two dealers can quote the same monthly payment built on different terms, rates and add-ons. Ask each one for the APR, the term, the amount financed including the 15% HST, and the total cost of borrowing. The offer with the smallest total cost, not the smallest payment, is usually the cheaper loan.
48 months or 84? What term length really costs
Longer terms are the easiest way to make a payment fit, which is why they turn up so often on bad-credit loans. On $25,000 at 27.00%, a poor-credit rate, the payment is about $857 over 48 months, $763 over 60, $704 over 72 and $665 over 84. The drop looks generous, but each extra year adds twelve more payments at a high rate.
The same pattern holds at any rate. At the bank average of 6.59%, picking 84 months over 60 adds about $1,863 in interest on $25,000, and the gap widens as the rate climbs. A long term also keeps you owing more than the car is worth for longer, which complicates a future trade-in.
If a 48-month payment is out of reach today, consider a mid-length term and a plan to refinance once your credit improves. Most lenders report on-time payments to the credit bureaus, so a steady record of payments made on time can move you into a cheaper band before the loan is half paid.
Self-employed in Conception Bay South
Without pay stubs, self-employed borrowers prove income another way. Expect to provide recent bank statements and your Notices of Assessment from the Canada Revenue Agency. Lenders usually look at the income you report after expenses, so a year with heavy write-offs can make your income look smaller than your actual cash flow.
You can strengthen the file with a down payment, a co-signer or a trade-in. Covering part of the HST, roughly $3,750 on a $25,000 vehicle, reduces the amount financed and the lender's risk at the same time. Keeping business and personal accounts separate also makes your statements far easier for a lender to read.
Local costs and protections in Newfoundland and Labrador
- Auto insurance in Newfoundland and Labrador is sold by private insurers, so compare several quotes. Lenders need proof of full coverage before you take delivery.
- Car sales in Newfoundland and Labrador are covered by provincial consumer protection law. Contact the provincial consumer protection office if a dealer misleads you.