When your credit is fair or damaged, buying a car in Coteau-du-Lac goes better if you plan the deal before choosing the vehicle. How much you put down, whether you trade in a vehicle and how old the car is all change what a lender will offer. Car Loan Finder is not a lender; we compare lenders and dealers for you through a soft inquiry that has no effect on your credit score. Once you see which options fit, you can shop with a budget already in hand.
Whether you sign in Salaberry-de-Valleyfield, about 7 km away, or in Vaudreuil-Dorion, about 16 km off, the dealer answers to the same Quebec regulator, the OPC. Closer still, Grande-Île and Saint-Clet are each about 6 km from Coteau-du-Lac, Les Cèdres about 10 km and Saint-Lazare about 12 km, with Sainte-Barbe and Hudson about 15 and 17 km away. Montréal, the province's largest city, is about 52 km away, and the town itself uses the J0P postal area.
Facts reviewed October 29, 2026 · See sources
Coteau-du-Lac car loan rates by credit score
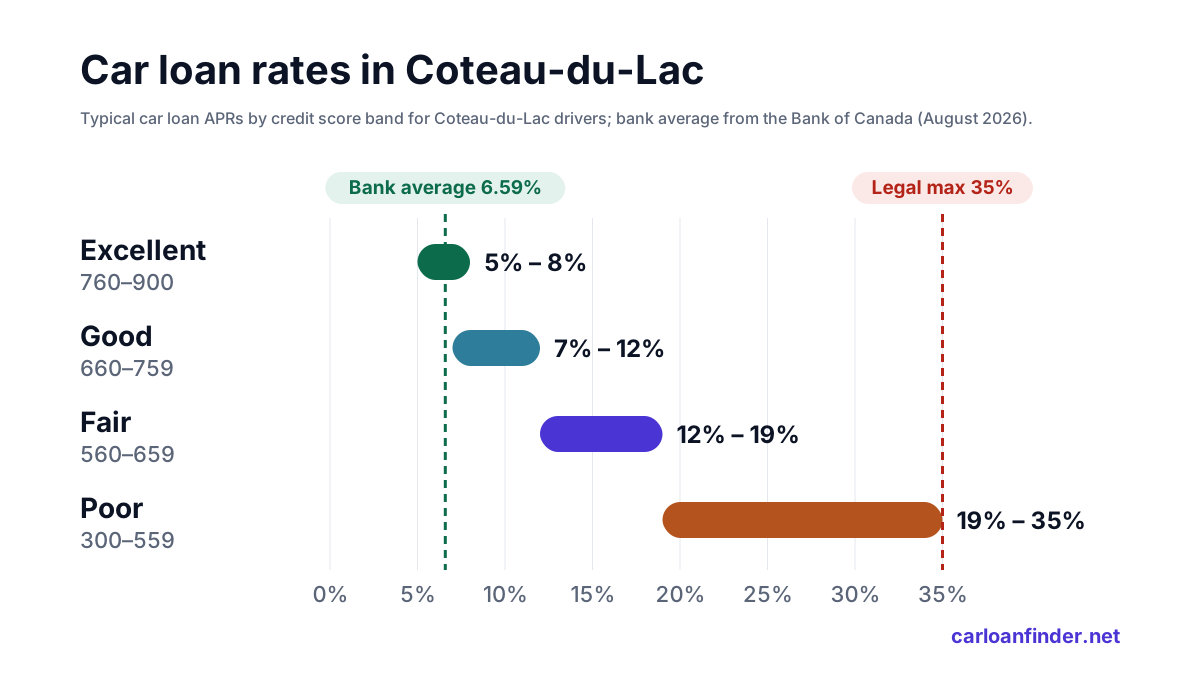
Most bank car loans are priced above prime. Dealer-arranged and specialist lenders set their own fixed rates, which is why credit score matters more than the Bank of Canada rate for bad credit borrowers.
| Credit tier | Equifax score | Typical APR | Example payment* |
|---|---|---|---|
| Excellent | 760–900 | 5% – 8% | $420/mo |
| Good | 660–759 | 7% – 12% | $457/mo |
| Fair | 560–659 | 12% – 19% | $535/mo |
| Poor | 300–559 | 19% – 35% | $704/mo |
| Legal maximum | — | 35% APR | Criminal Code, s. 347 |
* Score bands from Equifax Canada. Rate ranges are estimates published by Loans Canada, not quotes; your rate depends on income, debts, down payment, term and the vehicle. Example payment: $25,000 over 72 months at the middle of each range.
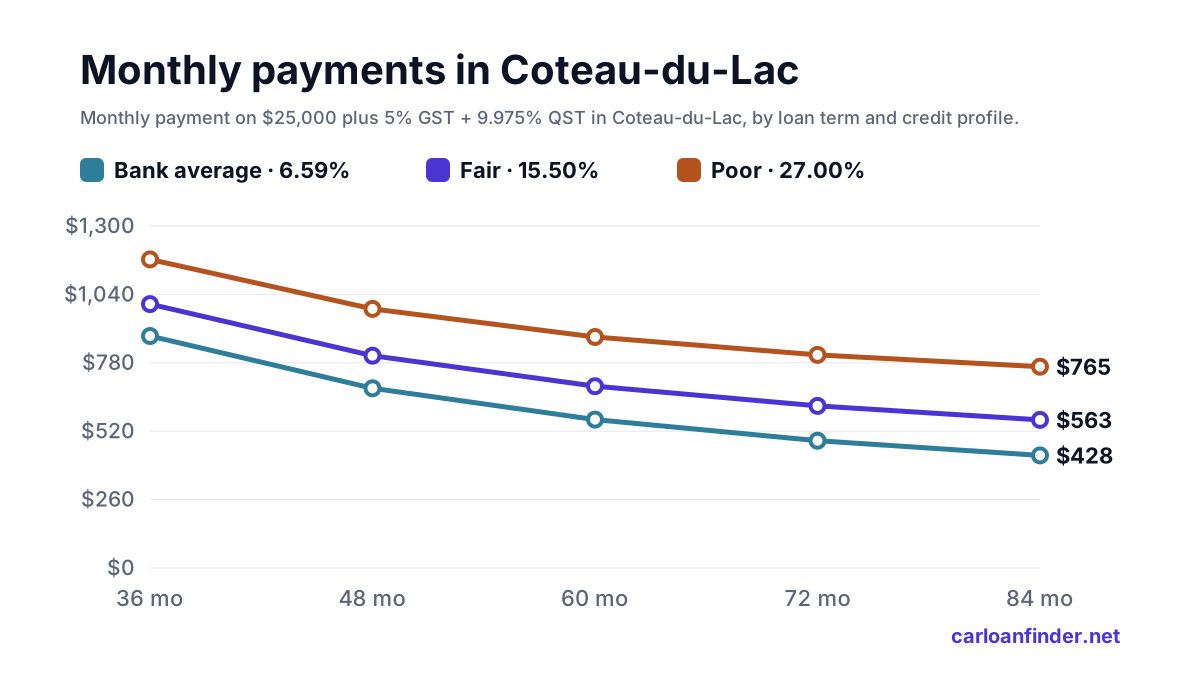
Monthly payments on a Coteau-du-Lac car loan
| Credit profile | 48 months | 60 months | 72 months | 84 months | Interest (72 mo) |
|---|---|---|---|---|---|
| Bank average 6.59% APR | $594 | $490 | $421 | $372 | $5,335 |
| Good 9.50% APR | $628 | $525 | $457 | $409 | $7,894 |
| Fair 15.50% APR | $702 | $601 | $535 | $489 | $13,551 |
| Poor 27.00% APR | $857 | $763 | $704 | $665 | $25,719 |
Monthly payment on $25,000 before tax, using the Bank of Canada average for bank borrowers and the middle of each published credit-tier range. In Quebec, 5% GST + 9.975% QST adds about $3,744 if it is financed.
Banks vs. specialist lenders in Coteau-du-Lac
Where you borrow matters as much as your credit score. Banks and credit unions usually offer the lowest rates but expect good credit; specialist lenders approve more credit profiles at higher rates. Here is how the options compare.
| Lender | Best for | How rates are set | Watch out for |
|---|---|---|---|
| Bank | Good to excellent credit | Usually priced above prime; close to the 6.59% bank average | Stricter approval; may require a larger down payment with lower scores |
| Credit union | Members with fair to good credit | Set by each credit union; often competitive with banks | Membership required; rules vary by province |
| Manufacturer finance | New vehicles, good credit | Promotional rates set by the automaker | A low rate may replace a cash rebate — compare both |
| Specialist (subprime) lender | Bad credit, proposals, newcomers | Higher fixed rates, up to the 35% legal maximum | Read the total cost of borrowing before you sign |
| Buy here, pay here dealer | When other lenders decline | Often the highest rates allowed | Limited vehicle choice; payments may not be reported to credit bureaus |
| Car Loan Finder | Every credit profile | Matched to lenders for your credit situation | One application; no impact on your credit score to see options |
How to get approved in Coteau-du-Lac with bad credit
- 1 Check your credit report You can get your credit report free from both Equifax and TransUnion. Dispute any errors before a lender sees them.
- 2 Set your budget Use the payment table above to find a payment that leaves room for insurance, fuel and maintenance.
- 3 Get pre-approved A pre-approval shows your likely rate and limit before you choose a car. Checking your options with Car Loan Finder is a soft inquiry.
- 4 Compare the total cost of borrowing Lenders must disclose the APR and total cost of borrowing in writing. Compare that figure, not only the monthly payment.
- 5 Keep the term as short as you can afford Longer terms lower the payment but cost more interest and raise the risk of owing more than the car is worth.
Car loans for every credit situation
Bankruptcy or consumer proposal
A first bankruptcy usually stays on your Equifax report for 6 years after discharge; a consumer proposal stays until 3 years after you complete it. Specialist lenders can approve you before those dates — often with a down payment.
No credit history
If you are new to Canada or have never borrowed, lenders look at income, employment and residency instead of a score. A larger down payment or a co-signer improves your options.
Self-employed
Expect to show recent bank statements and your Notices of Assessment from the Canada Revenue Agency instead of pay stubs.
Rebuilding after missed payments
On-time car payments are reported to the credit bureaus by most lenders. Choosing a payment you can always make is the fastest way to rebuild.
Matching the car to your credit
A lower purchase price is the simplest way to make a loan easier to approve. A reliable used vehicle often means a smaller loan, a shorter term and less interest overall. Before you buy, ask for the vehicle history and have it inspected by a mechanic you choose.
Dealers may offer an extended service contract with the loan. It is optional, it adds to the amount financed, and you pay interest on it. Ask for the payment with and without it so you can judge whether it is worth the cost.
Putting money down and trading in
Money down reduces what you borrow and shows the lender you share the risk, which matters most when your score is low. Even a modest amount can move an application from declined to approved with some lenders. Savings set aside over a few months also show the lender you can budget.
If you have a vehicle to trade, find out what it is worth and what you still owe before you visit a dealer. Positive equity works like a down payment. Negative equity is usually added to the new loan, which raises both the payment and the total cost.
Payments with fair or good credit
Fair credit, scores of 560–659, typically lands between 12–19%. At 15.50%, $25,000 costs about $702 a month over 48 months or $535 over 72 months. Good credit at 9.50% brings the 60-month payment to about $525, which shows how much a stronger score is worth before you apply.
Remember the tax. Quebec adds 5% GST and 9.975% QST, about $3,744 on a $25,000 vehicle, and that amount is usually financed along with the car unless you pay it up front. Ask the dealer to show the tax as its own line, so you can see exactly what you are borrowing.
Coteau-du-Lac rules that affect your car loan
- In Quebec, the SAAQ covers bodily injury while private insurers cover damage to your vehicle. Lenders need proof of coverage before you take delivery.
- Car dealers in Quebec are regulated by the Office de la protection du consommateur (OPC). Check that the dealer is licensed or registered before you sign, and contact the regulator if something goes wrong.
- Winter tires are mandatory in Quebec from December 1 to March 15 on vehicles registered in the province — budget for them if your car doesn’t come with a set.