With a low score, the first offer you see may come with a long term attached, pitched as the way to make the payment work. Before agreeing, it helps to see how little a longer term actually saves when the rate is high. Car Loan Finder is a matching service, not a lender. We check your options with a soft inquiry, which does not affect your credit score, and connect you with lenders that work with poor and fair credit in Hants County.
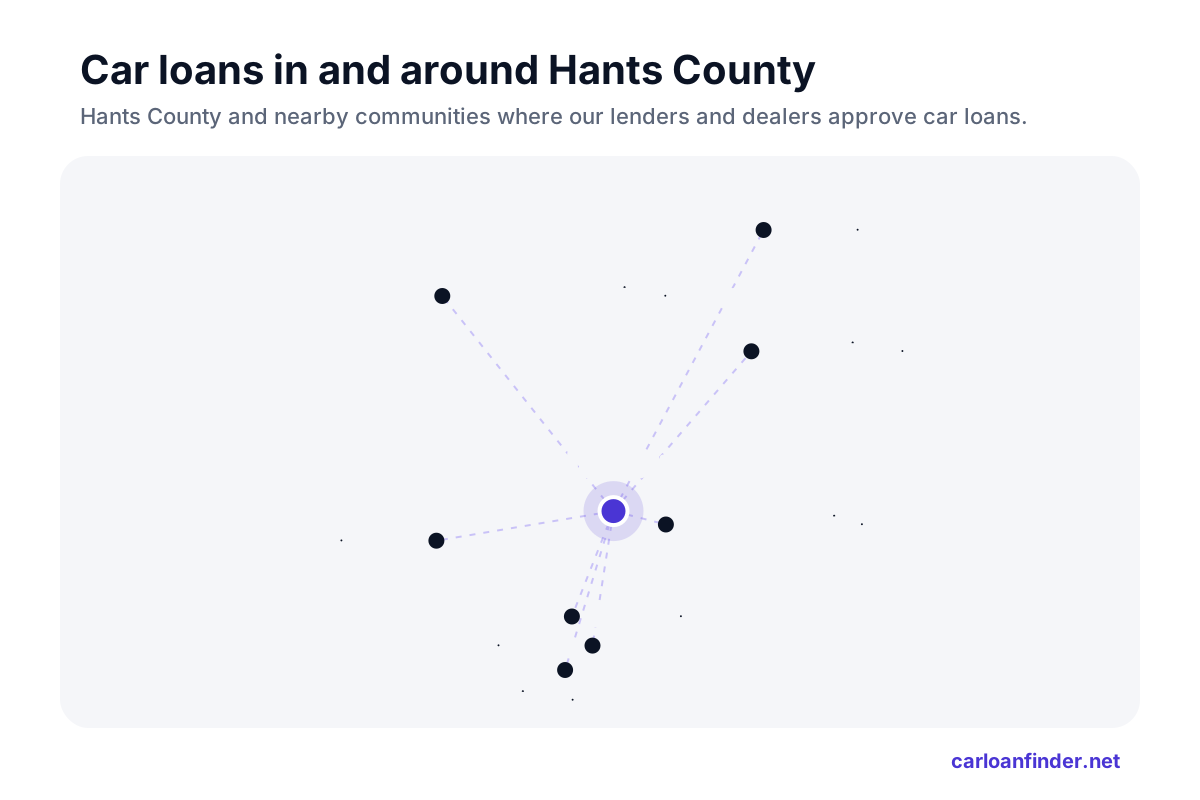
From Shubenacadie, about 6 km away, to Truro at roughly 34 km, the area offers several places to compare vehicles. Belnan (12 km), Elmsdale (15 km) and Enfield (18 km) are all close, with Upper Rawdon (19 km), Brookfield (23 km) and Densmores Mills (29 km) a little further. Halifax, Nova Scotia's largest city, is about 51 km away. The area here uses the B0N postal area, and lining up quotes from two or three of these communities is a simple way to test any offer.
Facts reviewed October 29, 2026 · See sources
What interest rate can you get in Hants County?
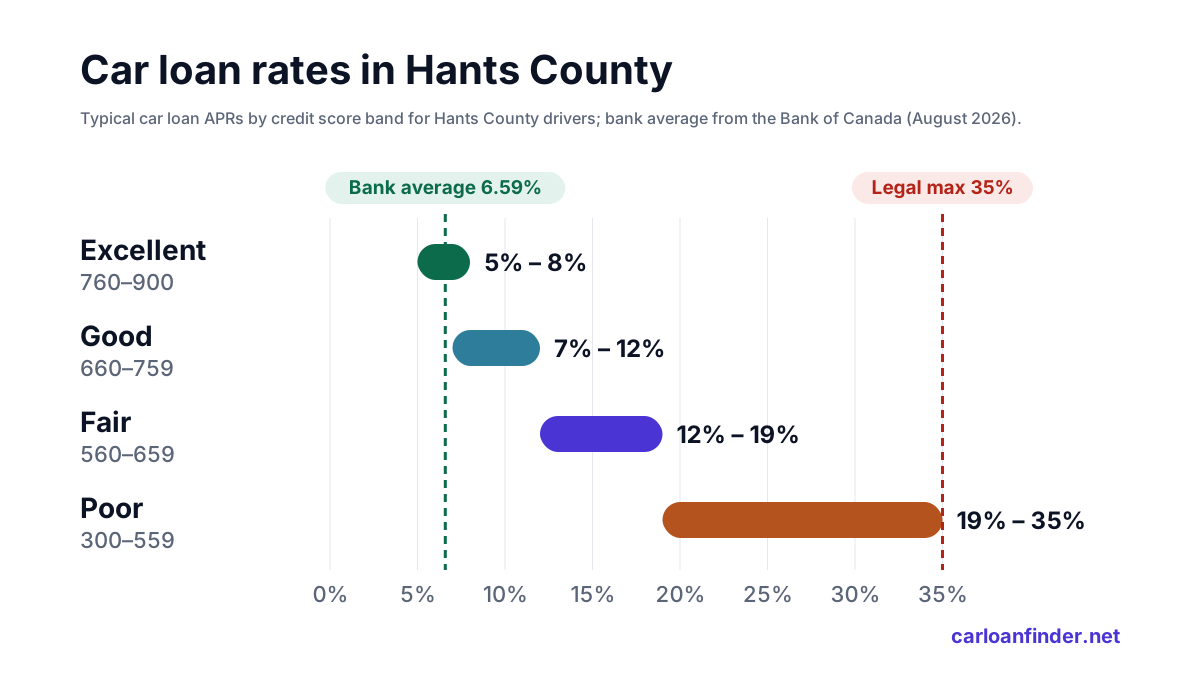
Most bank car loans are priced above prime. Dealer-arranged and specialist lenders set their own fixed rates, which is why credit score matters more than the Bank of Canada rate for bad credit borrowers.
| Credit tier | Equifax score | Typical APR | Example payment* |
|---|---|---|---|
| Excellent | 760–900 | 5% – 8% | $420/mo |
| Good | 660–759 | 7% – 12% | $457/mo |
| Fair | 560–659 | 12% – 19% | $535/mo |
| Poor | 300–559 | 19% – 35% | $704/mo |
| Legal maximum | — | 35% APR | Criminal Code, s. 347 |
* Score bands from Equifax Canada. Rate ranges are estimates published by Loans Canada, not quotes; your rate depends on income, debts, down payment, term and the vehicle. Example payment: $25,000 over 72 months at the middle of each range.
What a car loan costs in Hants County
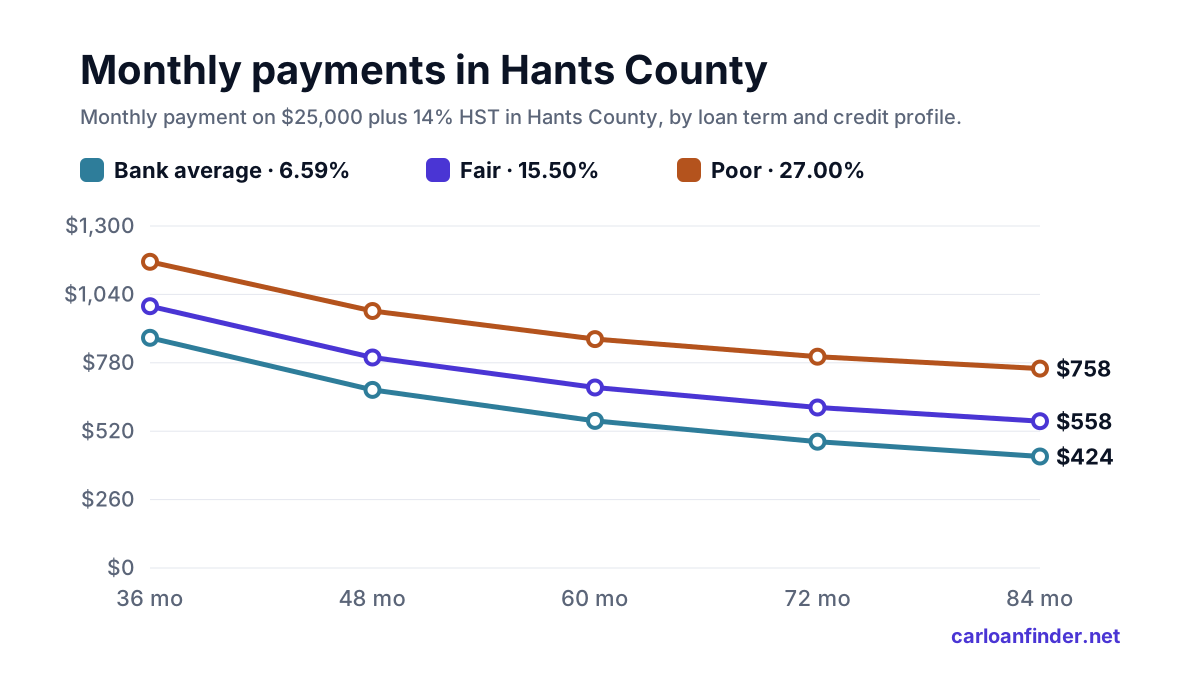
| Credit profile | 48 months | 60 months | 72 months | 84 months | Interest (72 mo) |
|---|---|---|---|---|---|
| Bank average 6.59% APR | $594 | $490 | $421 | $372 | $5,335 |
| Good 9.50% APR | $628 | $525 | $457 | $409 | $7,894 |
| Fair 15.50% APR | $702 | $601 | $535 | $489 | $13,551 |
| Poor 27.00% APR | $857 | $763 | $704 | $665 | $25,719 |
Monthly payment on $25,000 before tax, using the Bank of Canada average for bank borrowers and the middle of each published credit-tier range. In Nova Scotia, 14% HST adds about $3,500 if it is financed.
Compare car lenders in Hants County
Where you borrow matters as much as your credit score. Banks and credit unions usually offer the lowest rates but expect good credit; specialist lenders approve more credit profiles at higher rates. Here is how the options compare.
| Lender | Best for | How rates are set | Watch out for |
|---|---|---|---|
| Bank | Good to excellent credit | Usually priced above prime; close to the 6.59% bank average | Stricter approval; may require a larger down payment with lower scores |
| Credit union | Members with fair to good credit | Set by each credit union; often competitive with banks | Membership required; rules vary by province |
| Manufacturer finance | New vehicles, good credit | Promotional rates set by the automaker | A low rate may replace a cash rebate — compare both |
| Specialist (subprime) lender | Bad credit, proposals, newcomers | Higher fixed rates, up to the 35% legal maximum | Read the total cost of borrowing before you sign |
| Buy here, pay here dealer | When other lenders decline | Often the highest rates allowed | Limited vehicle choice; payments may not be reported to credit bureaus |
| Car Loan Finder | Every credit profile | Matched to lenders for your credit situation | One application; no impact on your credit score to see options |
How to get approved in Hants County with bad credit
- 1 Know your score band Canadian credit scores range from 300 to 900. Find your Equifax band in the rate table to estimate your rate.
- 2 Gather documents Recent pay stubs or bank statements, a valid driver’s licence and proof of your Hants County address.
- 3 Apply once, compare offers One application can reach several lenders, so you avoid multiple hard credit checks.
- 4 Watch for add-ons Extended warranties and insurance products added to the loan increase what you borrow. Ask for prices separately.
- 5 Sign only when the numbers match Check that the APR, term and total cost of borrowing on the contract match what you were quoted.
Your credit situation, explained
Bankruptcy or consumer proposal
A first bankruptcy usually stays on your Equifax report for 6 years after discharge; a consumer proposal stays until 3 years after you complete it. Specialist lenders can approve you before those dates — often with a down payment.
No credit history
If you are new to Canada or have never borrowed, lenders look at income, employment and residency instead of a score. A larger down payment or a co-signer improves your options.
Self-employed
Expect to show recent bank statements and your Notices of Assessment from the Canada Revenue Agency instead of pay stubs.
Rebuilding after missed payments
On-time car payments are reported to the credit bureaus by most lenders. Choosing a payment you can always make is the fastest way to rebuild.
Why 84 months saves less than it seems
At 27.00%, $25,000 over 72 months costs about $704 a month. Stretching it to 84 months only brings the payment down to about $665, yet you pay that high rate for a full extra year. At poor-credit rates, most of each early payment goes to interest.
The same pattern holds at lower rates. At the bank average of 6.59%, choosing 84 months over 60 adds about $1,863 in interest on $25,000. If a payment only works over 84 months, a cheaper vehicle may be the safer choice.
What a down payment does for a poor-credit file
A down payment does two jobs at once. It shrinks the amount you borrow, so you pay less interest, and it shows the lender you have a stake in the vehicle, which can lead to a better rate or an approval that would otherwise be out of reach.
Even a modest amount helps, especially after a bankruptcy or consumer proposal, where specialist lenders often ask for one. Money saved up over a few months before buying can change the offer more than any amount of negotiating at the dealership.
Comparing offers from Enfield to Truro
Enfield is about 18 km away and Truro about 34 km, with Elmsdale in between at 15 km. That range gives you several dealers to compare without a long trip, and a written quote from each makes the differences easy to spot.
Ask for the full price including fees and the 14% HST, about $3,500 on a $25,000 vehicle. If a quote only shows a monthly payment, ask for the rate, the term and the total cost of borrowing before going further.
Before you sign in Nova Scotia
- Auto insurance in Nova Scotia is sold by private insurers, so compare several quotes. Lenders need proof of full coverage before you take delivery.
- Car sales in Nova Scotia are covered by provincial consumer protection law. Contact the provincial consumer protection office if a dealer misleads you.